



Premium File
60 Q&A
$76.99$69.99
CIMA CIMAPRO17-BA2-X1-ENG Exam Questions & Answers, Accurate & Verified By IT Experts
Instant Download, Free Fast Updates, 99.6% Pass Rate
60 Questions & Answers
Last Update: Sep 17, 2026
$69.99
CIMA CIMAPRO17-BA2-X1-ENG Exam Screenshots
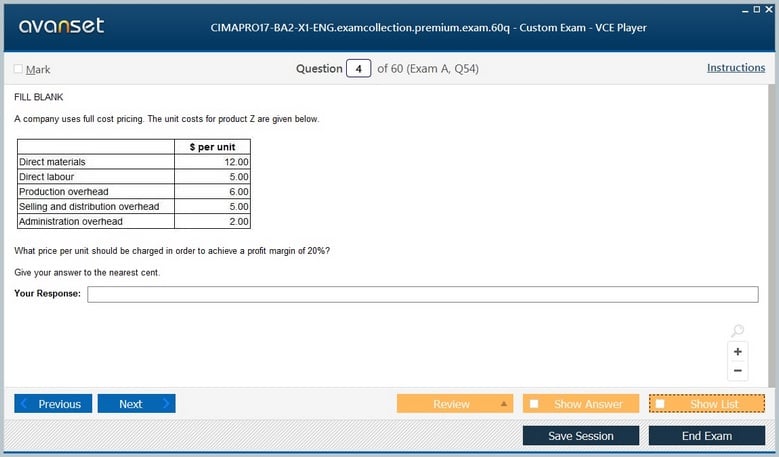
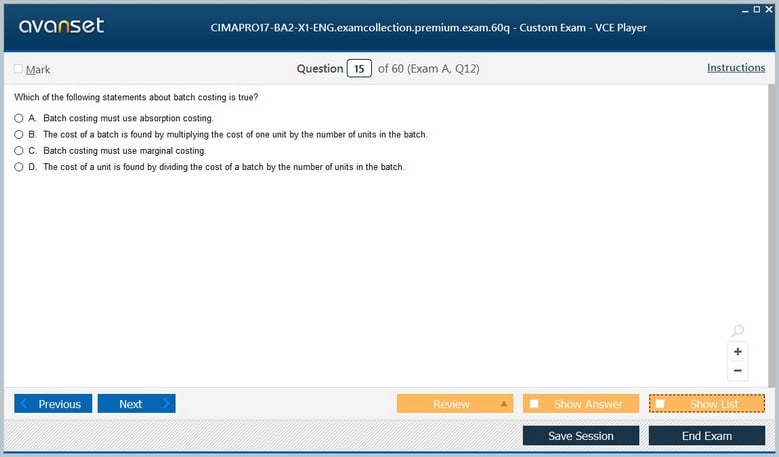
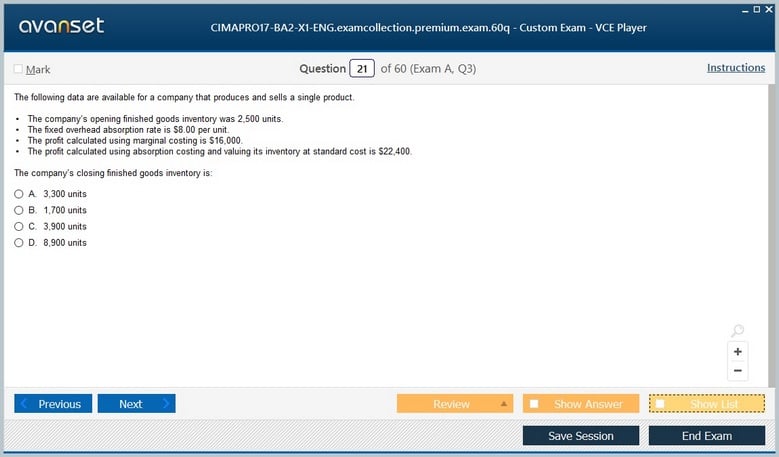
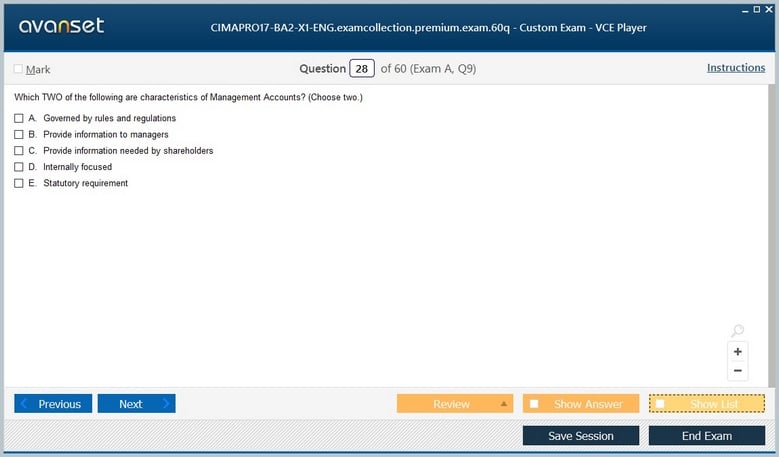
CIMA CIMAPRO17-BA2-X1-ENG Practice Test Questions in VCE Format
| File | Votes | Size | Date |
|---|---|---|---|
File CIMA.passcertification.CIMAPRO17-BA2-X1-ENG.v2026-09-26.by.lewis.25q.vce |
Votes 2 |
Size 467.89 KB |
Date Sep 26, 2026 |
CIMA CIMAPRO17-BA2-X1-ENG Practice Test Questions, Exam Dumps
CIMA CIMAPRO17-BA2-X1-ENG (E3 - Strategic Management Question Tutorial) exam dumps vce, practice test questions, study guide & video training course to study and pass quickly and easily. CIMA CIMAPRO17-BA2-X1-ENG E3 - Strategic Management Question Tutorial exam dumps & practice test questions and answers. You need avanset vce exam simulator in order to study the CIMA CIMAPRO17-BA2-X1-ENG certification exam dumps & CIMA CIMAPRO17-BA2-X1-ENG practice test questions in vce format.
CIMAPRO17-BA2-X1-ENG is a legacy question-tutorial identifier for BA2 Fundamentals of Management Accounting. BA2 itself remains a current subject in CIMA’s Certificate in Business Accounting, so the important distinction is between the old tutorial code and the living qualification. Current candidates should use the latest Cert BA syllabus and objective-test information while treating older material as practice for concepts that continue to matter.
The present BA2 syllabus is divided into four broad areas: the context of management accounting, costing, planning and control, and decision-making. The assessment is a two-hour, 60-question computer-based objective test available on demand. That structure rewards broad coverage and quick recognition, but the subject becomes much easier when candidates understand why each technique exists instead of treating formulas as isolated rules.
ExamCollection’s coverage of CIMA qualifications shows the wider route. BA2 complements BA1 business economics at certificate level and creates the foundation for P1 Management Accounting in the professional qualification. The progression is from basic techniques to using those techniques in more demanding operational decisions.
Financial accounting is designed around external reporting, while management accounting is built for planning, control, and decision support inside an organisation. BA2 candidates should understand that internal information can be tailored to a manager’s purpose, frequency, level of detail, and time horizon. A production supervisor may need daily efficiency measures while senior management may need a monthly view of cost behavior and profitability.
This distinction explains why relevance often matters more than formal reporting rules in management accounting. A technically precise report delivered after the decision is useless. Likewise, a highly detailed cost allocation can obscure the few figures a manager can actually influence. Study the information need first, then the technique that answers it.
Direct and indirect, fixed and variable, product and period, controllable and uncontrollable costs describe different characteristics of the same underlying expenditure. Candidates should be comfortable switching classifications depending on the question. Wages may be direct for one production process and indirect for another; a fixed cost may be fixed only within a relevant range.
Build revision examples from a single business. Take rent, materials, supervisor salaries, delivery costs, software subscriptions, and sales commissions, then classify them for different decisions. That exercise reveals why memorised lists are fragile. The classification follows the relationship between the cost and the cost object, activity, time period, or management responsibility.
BA2 introduces methods for accumulating and assigning cost, including absorption and marginal approaches. The aim is not simply to produce a unit cost. Managers use cost information to price products, value inventory, compare efficiency, and understand how volume changes affect profit. Different techniques can produce different answers because they treat fixed overhead differently.
When solving questions, state what is included in the unit cost and why. Under absorption costing, production overhead is allocated to units; under marginal costing, variable production cost is central to short-run contribution analysis. The exam often tests the conceptual consequence of the method as much as the arithmetic.
Contribution is one of the most important ideas in introductory management accounting because it shows how sales help cover fixed cost and then create profit. Once candidates understand contribution per unit and contribution-to-sales relationships, break-even, target profit, margin of safety, and simple product decisions become variations on the same logic.
Do not use cost-volume-profit analysis without checking its assumptions. Selling price, variable cost per unit, fixed cost, product mix, and activity behavior are treated as sufficiently stable within the relevant range. In real business those assumptions can move. BA2 questions may be simplified, but learning to identify the assumptions prepares candidates for later P1 work.
A budget expresses expected activity and resource use in financial or quantitative terms. Sales plans affect production, purchasing, labour, inventory, cash, and financing. BA2 candidates should understand the links between these budgets so they can recognise when one change has consequences elsewhere in the model.
Practise building the sequence rather than memorising separate formats. Start with expected sales, decide what inventory policy implies for production, translate output into material and labour needs, then consider overhead and cash timing. This process explains why budgets are coordination tools rather than simply spending limits.
Standards provide a benchmark for the quantity and price of resources expected under defined conditions. Variances then highlight where actual performance differs. BA2 candidates should calculate common material and labour variances, but they also need to understand that a variance is a prompt for investigation rather than proof of good or bad performance.
A favourable material-price variance can be accompanied by an adverse usage variance if lower-quality inputs create waste. An adverse labour-rate variance can be rational if more experienced staff reduce rework. Interpreting linked variances is more valuable than judging each one in isolation.
Short-run decisions often depend on future cash flows that change between alternatives. Sunk costs and unavoidable fixed costs are irrelevant to the choice, while incremental revenue, incremental cost, and opportunity cost can be decisive. This is the foundation of make-or-buy, special-order, shutdown, and product-mix reasoning.
The easiest way to avoid errors is to ask one question for every figure: “Will this cash flow change if the decision changes?” If not, it should not drive the comparison. Then consider non-financial factors such as quality, supplier reliability, customer relationships, capacity, and strategic dependence before reaching a recommendation.
BA2 introduces control because managers need feedback on whether plans are being achieved. Measures may focus on cost, revenue, efficiency, quality, or other operational outcomes. A good measure is understandable, timely, related to the objective, and sufficiently influenced by the person or team being assessed.
Be alert to dysfunctional behavior. If a buyer is rewarded only for reducing purchase price, the result may be lower quality or higher inventory. If a production manager is judged only on utilisation, unnecessary output may be produced. Management accounting is not neutral: measures influence behavior and should be designed with that consequence in mind.
Inventory and production decisions can reveal the difference between accounting presentation and economic reality. Building inventory may absorb fixed overhead into unsold units under some costing treatments, improving reported profit without improving cash or customer demand. Candidates should understand why managers need operational measures alongside accounting results so that production incentives do not encourage unnecessary stock.
Cash budgets are equally important because profitable operations can still face liquidity pressure. Credit sales create revenue before cash is collected; inventory can consume cash before it generates a sale; loan repayments and capital purchases create timing effects that an income statement does not show. A short cash forecast can therefore be more useful for immediate control than a profit forecast.
Responsibility accounting helps connect control with organisational structure. A manager should normally be assessed on items that the manager can influence, while senior management retains responsibility for broader strategic choices. Cost centres, revenue centres, profit centres, and investment centres reflect different decision rights. The performance measure should match those rights rather than reward or punish people for factors outside their authority.
Decision quality also depends on communicating uncertainty. When a model uses a single estimate for sales volume, material price, or labour hours, management may mistake an assumption for a fact. Even at foundation level, candidates benefit from asking how the result changes if the key assumption changes. That habit develops the analytical caution expected later in the professional qualification.
Ethics belongs in management accounting because internal numbers can influence pay, budgets, investment approval, and career outcomes. Pressure to manipulate a forecast, defer a cost, or choose a misleading performance measure can damage decisions even if no external financial statement is involved. Professional integrity starts with accurate internal information.
Overhead allocation should be treated as a model rather than a natural fact. Different bases can shift cost between products or departments even when total expenditure is unchanged. Candidates should understand why a cost driver is chosen and when a simple volume base may distort the economic relationship, especially in operations where support activity is not closely related to units produced.
Performance comparisons also need a fair benchmark. Comparing one month with another may be misleading if volume, product mix, prices, or seasonality changed. A flexible budget or rate-based measure can separate the effect of activity from efficiency. This is an early example of the analytical principle that later CIMA subjects develop more deeply: compare like with like before drawing a conclusion.
Break-even and contribution analysis are most useful when their assumptions are visible. A simple calculation may assume constant selling price, stable variable cost per unit, fixed costs that remain fixed across the relevant range, and a predictable sales mix. Real businesses can violate all of those assumptions. Candidates should be able to calculate the model and then explain what would change if capacity limits, discounts, overtime, inflation, or a different product mix altered the underlying economics. That distinction between numerical technique and managerial judgment is central to management accounting.
Objective tests reward fluency. Candidates should be able to calculate contribution, break-even, basic variances, budget figures, and relevant costs without spending excessive time deciding which formula to use. Short, frequent practice is more effective than rereading worked examples because recognition improves only when the candidate has to choose the method independently.
At the same time, always add a one-sentence interpretation after a calculation. Explain what the number means for the manager and which assumption could change the decision. That habit bridges the gap from the 2017 tutorial code to the current Cert BA exam and prepares the candidate for the more judgement-heavy management accounting that follows in CIMA’s professional qualification.
Go to testing centre with ease on our mind when you use CIMA CIMAPRO17-BA2-X1-ENG vce exam dumps, practice test questions and answers. CIMA CIMAPRO17-BA2-X1-ENG E3 - Strategic Management Question Tutorial certification practice test questions and answers, study guide, exam dumps and video training course in vce format to help you study with ease. Prepare with confidence and study using CIMA CIMAPRO17-BA2-X1-ENG exam dumps & practice test questions and answers vce from ExamCollection.
Purchase Individually
Site Search:

SPECIAL OFFER: GET 10% OFF

Pass your Exam with ExamCollection's PREMIUM files!
SPECIAL OFFER: GET 10% OFF
Use Discount Code:
MIN10OFF
A confirmation link was sent to your e-mail.
Please check your mailbox for a message from support@examcollection.com and follow the directions.

Download Free Demo of VCE Exam Simulator
Experience Avanset VCE Exam Simulator for yourself.
Simply submit your e-mail address below to get started with our interactive software demo of your free trial.