



Premium File
103 Q&A
$76.99$69.99
ASQ CQA Exam Questions & Answers, Accurate & Verified By IT Experts
Instant Download, Free Fast Updates, 99.6% Pass Rate
CQA Premium File: 103 Questions & Answers
Last Update: Sep 21, 2026
CQA Training Course: 101 Video Lectures
$74.99
ASQ CQA Exam Screenshots
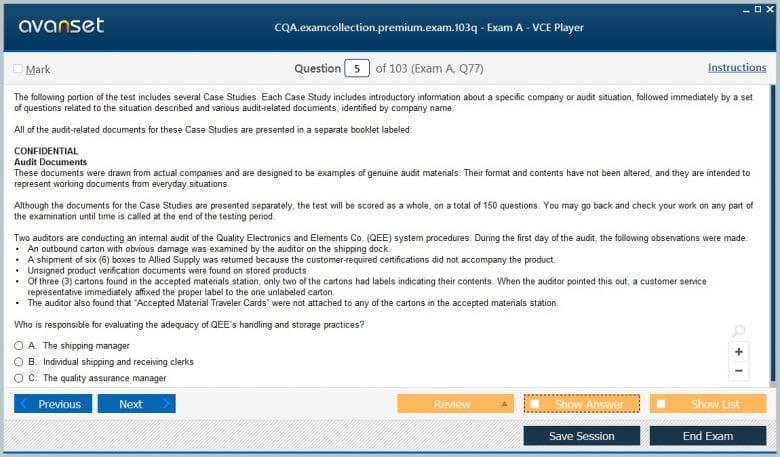
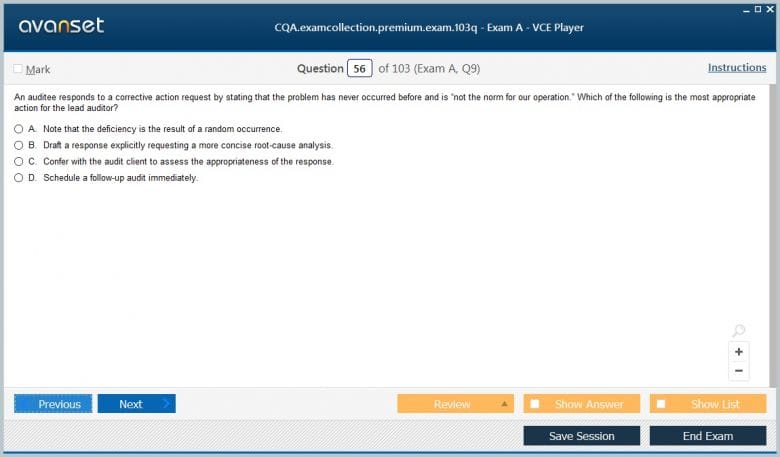
ASQ CQA Practice Test Questions in VCE Format
| File | Votes | Size | Date |
|---|---|---|---|
File ASQ.examanswers.CQA.v2026-09-01.by.robyn.67q.vce |
Votes 1 |
Size 89.33 KB |
Date Sep 01, 2026 |
File ASQ.Test4prep.CQA.v2019-06-14.by.Calista.66q.vce |
Votes 3 |
Size 86.5 KB |
Date Jun 15, 2019 |
ASQ CQA Practice Test Questions, Exam Dumps
ASQ CQA (Certified Quality Auditor) exam dumps vce, practice test questions, study guide & video training course to study and pass quickly and easily. ASQ CQA Certified Quality Auditor exam dumps & practice test questions and answers. You need avanset vce exam simulator in order to study the ASQ CQA certification exam dumps & ASQ CQA practice test questions in vce format.
ASQ's Certified Quality Auditor credential focuses on the discipline of evaluating systems, processes, and controls against defined criteria. A professional auditor does more than find errors. The role requires planning a fair and risk-informed audit, gathering sufficient objective evidence, communicating findings accurately, understanding corrective-action follow-up, and preserving independence and professional conduct throughout the engagement.
The current computer-based CQA exam contains 165 questions, with 150 scored and 15 unscored, and an appointment of five hours and 18 minutes. ASQ treats the exam as open book, and approximately 10 to 15 percent of the questions are presented as case studies. ASQ normally expects eight years of full-time paid experience in relevant areas, with three of those years in a decision-making role; qualifying education can waive part of the broader experience requirement. ASQ began testing the new 2026 CQA Body of Knowledge with the April 2026 window, so older study plans should be reconciled to the current outline.
Among ASQ certifications, CQA is distinctive because its audit methods apply across industries. A quality engineer may use data to improve a process, while an auditor asks whether requirements are defined, controls are implemented, evidence is reliable, and the system is effective. The two perspectives reinforce each other but should not be confused.
An audit begins by defining what will be evaluated and why. Criteria can include standards, regulations, contracts, procedures, policies, specifications, or other documented requirements. Scope defines the organizational units, locations, processes, products, systems, or time period included. Objectives explain the purpose, such as determining conformity, evaluating effectiveness, qualifying a supplier, investigating risk, or supporting management oversight.
Ambiguity at this stage creates problems later. Auditors should not invent requirements after finding something they dislike, and auditees should not have to guess what evidence is relevant. A clear plan identifies applicable criteria, key processes, audit methods, timing, resources, and responsibilities. For complex audits, previous findings, process performance, complaints, changes, and known risks can help determine where to sample more deeply.
Risk-based planning does not mean ignoring low-risk areas completely. It means allocating attention intelligently. A process with severe potential consequences, major recent change, poor performance, or recurring findings may justify more time than a stable administrative activity. The rationale should remain defensible and consistent with the audit objective.
Audit results matter only if users trust the process. Auditors should act with integrity, maintain confidentiality, avoid conflicts of interest, report evidence honestly, and stay within the limits of their competence. Independence does not always mean the auditor is external to the organization, but the auditor should be sufficiently free from responsibility for the work being audited to make an objective evaluation.
Professional skepticism is different from hostility. An auditor should neither assume everything is compliant nor approach the auditee as an adversary. Questions should seek understanding and evidence. Respectful interviews, transparent sampling, and accurate summaries reduce defensiveness and make it more likely that the audit discovers how work actually happens rather than how people think the auditor wants it described.
Confidential information may include customer data, employee records, intellectual property, security information, investigation details, or commercially sensitive material. Audit teams should understand access rules, record handling, retention, and disclosure expectations before collecting more information than they can appropriately protect.
Document review can help an auditor understand the system before fieldwork. Policies, procedures, process maps, metrics, organization charts, previous audit reports, corrective actions, complaints, training records, risk assessments, and management-review outputs can reveal where questions should be concentrated. The purpose is not to complete the audit from a desk but to develop useful hypotheses and sampling plans.
An audit schedule should follow process logic where practical. For example, a product audit may trace requirements through planning, purchasing, production, inspection, release, and complaint handling rather than visiting departments in an arbitrary order. Following the trail makes interfaces visible. It can reveal where a requirement is lost between functions even when each department's local procedure appears acceptable.
Checklists can support consistency but should not become scripts that prevent investigation. A good auditor uses prepared questions while remaining alert to evidence that opens a more important line of inquiry. If records show repeated emergency approvals, the auditor may need to explore planning or change control even if that topic was not emphasized in the original checklist.
Audit evidence can come from interviews, observation, records, data, documents, physical conditions, system transactions, and other verifiable sources. No single type is automatically best. Interviews can explain a process but should often be corroborated. Records can show what was documented but may not show actual behavior. Observation captures real activity but only for a limited period. Triangulation strengthens confidence.
Sampling is unavoidable because auditors rarely examine every transaction. The sample should be appropriate to the objective, risk, population, and time available. Random, stratified, judgmental, or targeted approaches can all be legitimate when their limitations are understood. A small sample cannot prove universal conformity, while one failure in a high-risk control may be significant even if most sampled records are acceptable.
Traceability is important when developing findings. The auditor should be able to show which requirement applies, what objective evidence was observed, and why the evidence demonstrates conformity or nonconformity. Vague statements such as inadequate control are weak because they do not explain the condition. Precise evidence makes corrective action more useful and reduces arguments about interpretation.
A strong nonconformity statement connects requirement and evidence. It identifies what should have happened and what was observed instead. Classification systems such as major, minor, critical, or observation vary by audit program, so auditors should apply the governing definitions consistently rather than using severity labels based on personal instinct.
Auditors should normally avoid designing the corrective action for the auditee. Suggesting the exact solution can compromise independence and transfer ownership away from process management. The auditor can clarify the finding, explain the evidence, and later evaluate whether corrective action addresses the cause. The organization responsible for the process should decide how to correct and improve it within applicable constraints.
Positive practices can also be reported when the audit program supports them, but praise should not dilute findings or turn the report into a morale exercise. The central purpose remains objective evaluation. Conclusions should accurately reflect the evidence sampled and should not claim more certainty than the audit can support.
The case-study portion of the CQA exam is important because audit work unfolds over time. A scenario may describe planning information, interviews, records, conflicting explanations, and follow-up evidence. Candidates need to decide what should happen next rather than merely identify a definition. The strongest answer often preserves due process: verify the applicable criterion, collect enough evidence, avoid premature conclusions, and maintain the auditor's role.
When information conflicts, the response should be evidence driven. If a supervisor says a procedure is always followed but sampled records show otherwise, the auditor should not simply choose one source. Additional sampling, direct observation, or examination of system controls may clarify the real process. Similarly, an isolated unusual record may justify investigation without automatically proving a systemic failure.
Time management matters with cases because extensive narratives can tempt candidates to reread repeatedly. Identify the audit stage, the governing requirement, the evidence already available, and the decision being asked. This structure reduces distraction from scenario details that do not change the professional action.
Correction resolves the immediate condition; corrective action addresses the cause of the nonconformity to reduce recurrence. An auditor evaluating a response should determine whether the organization understood the extent of the problem, analyzed cause appropriately, implemented actions, and verified effectiveness. Closing a finding because a new procedure was issued can be premature if there is no evidence the new process works.
Root-cause analysis should match complexity. Simple cause-and-effect chains may be adequate for straightforward problems, while recurring or high-risk findings may need deeper analysis. Candidates should be cautious when human error is offered as the final cause. The useful question is why the error occurred and why existing controls failed to prevent or detect it.
Effectiveness can be demonstrated through later records, trend data, repeat sampling, observation, audit, performance measures, or other evidence appropriate to the action. The time needed depends on the process. A monthly activity may require multiple cycles before effectiveness can be judged, while a configuration control might be verified immediately after implementation and then monitored.
Organizations that conduct multiple audits need a managed audit program. That includes objectives, risk-based schedules, auditor selection, competence, independence, resources, methods, reporting, record retention, escalation, and review of program performance. Audit frequency should reflect risk and history rather than follow the same calendar interval for every process without thought.
Auditor competence includes knowledge of audit principles, relevant standards or regulations, industry processes, interviewing, sampling, evidence evaluation, and report writing. Technical specialists may support an audit when specialized expertise is needed, but they still need direction on evidence and confidentiality. Witnessing, supervised audits, feedback, training, and performance review can help maintain competence.
Program metrics should measure more than number of audits completed. Repeat findings, overdue actions, cycle time, coverage of high-risk processes, auditor calibration, stakeholder feedback, and the usefulness of systemic insights may be more informative. Broader quality management principles help connect audit information to leadership decisions instead of allowing reports to disappear into a compliance archive.
The audit method is portable, but criteria and consequences vary. In pharmaceutical operations, for example, data integrity, validated state, deviations, CAPA, and supplier controls can carry direct product and patient implications; candidates interested in that environment may encounter the specialized pharmaceutical GMP framework. In software, configuration, lifecycle evidence, verification, validation, and change control may dominate the audit trail.
Auditors therefore need enough subject knowledge to understand the process without replacing objective criteria with personal preference. A technically elegant practice is not a nonconformity unless it is required by the audit criteria. Conversely, a weak practice can still deserve management attention even if it does not qualify as a formal finding. Clear separation between requirement, evidence, risk observation, and recommendation protects report quality.
Remote and technology-assisted auditing can change how evidence is obtained but not the underlying principles. Screen sharing, electronic records, video observation, data analysis, and virtual interviews can increase reach, yet access limitations, authenticity, confidentiality, and reduced physical context must be considered. Audit planning should adapt methods to maintain sufficient evidence.
CQA preparation should repeatedly ask: What is the criterion? What evidence would be sufficient? What is the risk? Is the auditor still within scope? Has a conclusion been reached too early? What follow-up would demonstrate effectiveness? This sequence is more durable than memorizing lists because it mirrors the judgment required in case studies and real audits.
Open-book status should not become a substitute for knowing the current 2026 Body of Knowledge. Candidates should organize references around the official outline, mark frequently used material, and practice finding support quickly. The long exam appointment helps with complex scenarios, but time can still disappear if every question becomes a research exercise.
The strongest CQA candidate is disciplined about evidence and proportion. Audit thoroughly enough to support a conclusion, report exactly what the evidence demonstrates, preserve independence, and follow significant findings until effectiveness is credible. That professional restraint is what turns an audit from a checklist inspection into a trusted part of the quality system.
Go to testing centre with ease on our mind when you use ASQ CQA vce exam dumps, practice test questions and answers. ASQ CQA Certified Quality Auditor certification practice test questions and answers, study guide, exam dumps and video training course in vce format to help you study with ease. Prepare with confidence and study using ASQ CQA exam dumps & practice test questions and answers vce from ExamCollection.
Purchase Individually
ASQ CQA Video Course
Site Search:

SPECIAL OFFER: GET 10% OFF

Pass your Exam with ExamCollection's PREMIUM files!
SPECIAL OFFER: GET 10% OFF
Use Discount Code:
MIN10OFF
A confirmation link was sent to your e-mail.
Please check your mailbox for a message from support@examcollection.com and follow the directions.

Download Free Demo of VCE Exam Simulator
Experience Avanset VCE Exam Simulator for yourself.
Simply submit your e-mail address below to get started with our interactive software demo of your free trial.